
Mortgage lenders have spent years investing in technology to solve specific problems. One system improves the borrower application, another manages documents, while others support credit, verification, communication, analytics, or downstream processing. None of those tools is necessarily the problem. The bigger issue is what happens when they operate independently.
A lender can have strong technology across every part of the mortgage process and still rely on employees to move information between systems, reconcile duplicate data, track down documents, and work around disconnected workflows. That is why the next phase of mortgage technology should not be about simply adding or removing tools. It should be about whether those tools operate on a connected foundation where applications, workflows, documents, data, and downstream systems can work together.
Key Insights at a Glance
- The problem is not how many mortgage tools a lender uses, but whether those tools can work together.
- Disconnected systems create manual work between otherwise useful technologies.
- Integration affects daily lending operations, not just IT.
- A connected foundation can help lenders modernize without replacing every existing system.
- Stronger connectivity creates better conditions for analytics, automation, and AI.
- The value of the technology foundation is practical: clearer data flow, fewer workarounds, and greater flexibility as lender needs evolve.
Table of Contents
Point Solutions Are Not the Problem
Specialized technology has an important place in mortgage lending. Lenders have different needs across point of sale, loan origination, verification, document management, closing, analytics, and servicing. It would be unrealistic to expect one product to perform every function equally well.
The issue begins when each solution becomes its own island.
That concern already shows up in how lenders evaluate technology partners. A 2024 Fannie Mae survey of nearly 200 senior mortgage executives identified cost, functionality, and integration capabilities as the three most important criteria when selecting technology service providers. Respondents also noted that costly upfront integration challenges could discourage lenders from considering new providers.
That distinction matters. A new tool may solve one immediate problem while creating another connection that IT teams need to maintain, another source of data employees need to reconcile, and another workflow loan officers need to learn.
The question should therefore be less about whether a lender has “too many tools” and more about whether those tools operate as part of a connected environment.
Where Fragmentation Becomes an Operational Problem
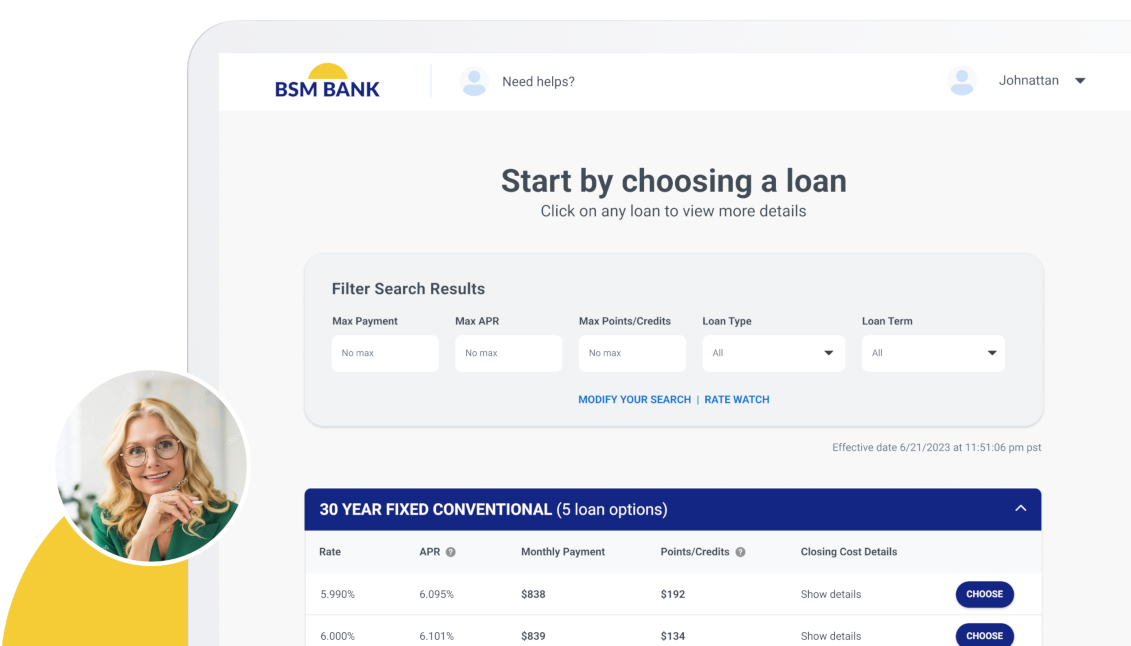
Consider a borrower completing a digital mortgage application.
They enter employment, income, asset, and property information, upload required documents, and submit the application. From the borrower’s perspective, the front end may feel seamless.
Behind the scenes, however, the loan officer may need to move into another system to continue working the file. Information collected during the application may need to be reviewed or entered again downstream. Documents may live in a separate workflow. Teams may need to check multiple systems to understand what has been completed and what still needs attention.
Each system may be doing its job. The problem is the work created between them.
That is where fragmentation becomes an operational issue rather than simply an IT issue. Employees become responsible for connecting systems manually by checking status, reconciling information, moving data, and making sure the next step actually happens.
The gap between front-end and back-end modernization is longstanding. In a 2019 study, Fannie Mae reported that more lenders prioritized improving the front-end consumer experience than back-end operational efficiency. Lenders also viewed their front-end transformation efforts as more successful, while back-end modernization remained more difficult because mortgage origination involves many systems, stakeholders, and large volumes of data moving between them.
That matters because a polished digital application does not automatically create an efficient lending process. If the borrower enters information digitally but an employee has to recreate or reconcile that information later, the bottleneck has simply moved further downstream.
The operational pressure is also difficult to ignore. More recent Mortgage Lender Sentiment Survey results from Fannie Mae identified business process streamlining and cost-cutting among lenders’ major business priorities.
In that environment, connectivity has a direct business purpose. The goal is not to integrate systems simply because integration sounds better. It is to reduce the amount of manual work created between otherwise useful technologies.
What a Connected Foundation Changes
Now consider the same mortgage journey on a more connected foundation.
The borrower still interacts with a digital application. The lender may still use a POS, LOS, verification providers, document tools, and other specialized technologies. The difference is that information has clearer paths between them.
Application data can move into downstream systems without requiring employees to recreate the same information. Workflow events can help indicate when the next step needs to happen. Status information can move between the systems and experiences that need it.
The lender still has multiple tools. What changes is how much human effort is required to make those tools behave like one lending process.
This is the practical value behind concepts such as APIs, shared data structures, and reusable workflow logic. The architecture matters because of what it enables operationally.
A connected foundation can help lenders:
Subscribe to BeSmartee 's Digital Mortgage Blog to receive:
- Mortgage Industry Insights
- Security & Compliance Updates
- Q&A's Featuring Mortgage & Technology Experts
- Reduce duplicate data entry between systems
- Create clearer handoffs between borrower-facing and operational workflows
- Add new capabilities without rebuilding every existing connection
- Preserve important systems while modernizing specific parts of the lending journey
- Create more consistent data for analytics and future automation
This also gives lenders a more realistic path to modernization.
A connected foundation does not require an institution to replace its LOS or eliminate every specialized provider. Instead, the lender can preserve systems that continue to perform important functions while improving how newer experiences, workflows, and services connect with them.
The result is not one platform doing everything. It is an environment where different technologies have clearer ways to work together.
Why the Foundation Matters More as AI Expands
The same principle becomes even more important as lenders explore AI.
Adding an AI capability to a disconnected workflow does not automatically make the overall process more efficient. AI still needs access to appropriate information, a clearly defined place within the workflow, and controls around how outputs are used and validated.
Lender attitudes toward AI reinforce this connection between infrastructure and operational value. In Fannie Mae’s research on AI adoption in mortgage lending, integration complexity with existing infrastructure was identified as one of the largest adoption challenges among lenders that had not used AI or machine learning. At the same time, 73% of respondents said improving operational efficiency was their primary motivation for adopting AI or machine learning.
Those two findings point to the same underlying challenge.
If operational efficiency is the goal, the technology surrounding AI has to allow information to move where it is needed. Otherwise, the lender risks adding another tool that employees must access separately, interpret independently, or manually connect with the rest of the process.
A stronger foundation does not guarantee that every AI initiative will succeed. It does, however, create better conditions for introducing automation and intelligence into existing workflows without adding another disconnected layer.
Where Bright Fits
Bright applies this connected-foundation approach to the mortgage experience.
Rather than asking lenders to replace every technology already supporting their business, Bright is designed to work with existing lending infrastructure and connect borrower-facing experiences with the systems and workflows supporting the rest of the loan journey.
For lenders, the value is less about architecture terminology and more about creating a more consistent path from digital intake into the processes that follow. For example, borrower and application data captured through Bright can move into the lender’s existing LOS, while configurable workflows help determine what happens next based on the lender’s programs and processes. This makes the idea of a “connected foundation” more practical: information captured at the front of the journey can continue into the systems and workflows employees use next, rather than becoming another isolated source of data.
That approach gives lenders room to improve the digital experience without treating every new requirement as another standalone technology project. It also provides a more flexible base for continued modernization as workflows and technology needs change.
The practical goal is straightforward: reduce the gaps between the experience a borrower sees and the operational systems employees depend on.Bright’s role is not to replace every specialized technology a lender uses. It is to provide a connected foundation through which borrower experiences, data, systems, and workflows can work together.
Quick Q&A: Connected Mortgage Technology
Q: Does a lender need fewer point solutions?
A. Not necessarily. Specialized tools can provide important capabilities. The key question is whether those tools can exchange information and participate in connected workflows.
Q: Does a connected platform mean replacing the LOS?
A. No. A connected platform can work alongside existing loan origination infrastructure and help bridge borrower-facing experiences with downstream systems.
Q: What is the biggest operational benefit?
A. Better connectivity can reduce the manual work created between systems, including duplicate data entry, status checking, information reconciliation, and workflow coordination.
Q: Why does connectivity matter for AI?
A. AI is easier to introduce into lending operations when relevant data can move through clearly defined workflows. A connected foundation helps prevent AI from becoming another isolated technology layer.
Roundup
Mortgage lenders do not necessarily have too many tools. The bigger issue is whether those tools can work together. Point solutions can continue to play an important role, but when employees have to re-enter information, reconcile systems, check multiple platforms, or create manual workarounds to keep a loan moving, the technology stack is not functioning as one connected lending environment.
That is why the next phase of mortgage modernization should focus less on counting tools and more on strengthening the foundation beneath them. The lenders best positioned to adapt will not necessarily be those with the fewest systems or the most features, but those whose technology can connect, exchange data, support consistent workflows, and make it easier to add what comes next.
Is your mortgage tech stack creating more manual work between systems than it solves? See how Bright connects borrower experiences, data, and workflows with the lending infrastructure you already use.