
Credit analysis is only as strong as the financial information behind it.
Before analysts can evaluate repayment capacity, identify trends, or make a lending recommendation, borrower financials must be reviewed, organized, standardized, and prepared for analysis.
When that information is inconsistent, incorrectly categorized, or prepared differently across reporting periods, the issue extends beyond financial spreading. It can change the financial picture analysts use to evaluate the borrower.
That makes data quality a credit quality issue.
The objective is not simply to catch more mistakes. It is to give credit professionals a reliable and consistent financial foundation so their judgment is applied to the strongest information possible.
Key Takeaways
- Data quality can influence the credit analysis and decisions that follow.
- Financial spreading inconsistencies extend beyond simple transcription mistakes.
- Review can identify problems, but it does not replace consistent financial preparation.
- Standardization strengthens borrower comparisons, trend analysis, and credit review.
- FlashSpread helps lenders prepare cleaner, more consistent financial data before analysis begins.
Data Quality Starts Before Credit Analysis
When lenders think about financial spreading mistakes, incorrect data entry is often the first risk that comes to mind. But borrower financials arrive in different formats, use different terminology, cover different reporting periods, and organize similar information in different ways.
Preparing that information consistently requires interpretation before analysis can begin.
Variation can enter the spread through several areas:
- Transcription: A value is copied incorrectly or entered into the wrong field.
- Categorization: Similar line items are treated differently across analysts or reporting periods.
- Calculations: Formulas, totals, ratios, or adjustments are applied inconsistently.
- Period alignment: Financial information from different years or entities is compared incorrectly.
- Version control: Teams review or update different versions of the same spread.
The concern is not simply that one number may be wrong. It is that these differences can shape the financial information analysts ultimately rely on.
Financial spreading is not the final output. It creates the data foundation for the credit analysis that follows.
When Data Quality Changes the Credit Picture
Small inconsistencies can have a larger impact once financial information feeds ratios, cash flow calculations, historical trends, debt service analysis, and lending recommendations.
Consider a line item categorized differently from one year to the next. Each underlying number may be accurate, but the resulting trend could suggest a change in borrower performance that actually reflects a change in how the information was prepared.
The same issue can occur across borrowers. If similar adjustments or calculations are handled differently from one deal to another, analysts are no longer evaluating those opportunities from the same financial foundation.
That creates a broader credit quality concern.
Analysts need to distinguish changes in the borrower’s actual performance from differences introduced during preparation. When the underlying data is inconsistent, they may spend additional time reconciling the information before they can confidently interpret it.
More importantly, the quality and consistency of the inputs can influence the quality of the analysis coming out.
For lending leaders, the strategic question is therefore not simply whether every number has been entered correctly. It is whether credit teams can trust that financial information has been prepared consistently enough to support sound comparisons and informed credit decisions.
Review Alone Does Not Create Consistency
Credit teams already review financial spreads for good reason.
Reconciliations, second reviews, and analyst verification can catch many issues before information moves deeper into the credit process. These controls remain important, but they are strongest when they validate a consistent process rather than compensate for unnecessary variation.
Some problems are easy to identify. A total that does not reconcile immediately signals that something requires attention.
Others are much less obvious. A line item categorized differently from the previous period may still produce a spread that appears mathematically correct. The analyst has to recognize that the comparison itself has changed.
Subscribe to BeSmartee 's Digital Mortgage Blog to receive:
- Mortgage Industry Insights
- Security & Compliance Updates
- Q&A's Featuring Mortgage & Technology Experts
Adding more review can therefore increase confidence, but it does not address where inconsistent data originated.
A stronger approach improves data quality earlier. When unnecessary variation is reduced before analysis begins, review can focus on genuine exceptions, borrower-specific circumstances, and the areas where experienced credit judgment creates the most value.
Building Data Quality Into Financial Spreading
Standardization is often discussed as a way to make financial spreading faster. Its strategic value goes further.
Consistent financial preparation gives analysts a clearer basis for evaluating borrowers across deals, reporting periods, and entities. Similar information is treated more consistently, meaningful changes are easier to identify, and credit teams spend less time determining whether differences came from the borrower or the preparation process.
This strengthens several parts of the credit process:
- Borrower comparisons: Analysts begin from a more consistent financial foundation.
- Trend analysis: Period-to-period changes are less likely to reflect differences in preparation.
- Credit review: Teams can focus on borrower performance instead of reconciling avoidable inconsistencies.
- Reporting: Standardized information creates more reliable inputs for downstream analysis.
- Portfolio monitoring: Consistent data makes borrower performance easier to track over time.
Lenders can strengthen data quality further by focusing on four principles.
First, standardize how borrower financial information is prepared across analysts and deals. Second, surface missing, inconsistent, or unexpected information before it moves deeper into credit review. Third, make verification clear so analysts can easily review the information supporting their analysis. Finally, preserve experienced judgment for the exceptions and borrower-specific issues that actually require it.
The objective is not to remove analysts from the process. It is to give them a stronger starting point.
Standardization does not replace professional judgment. It makes that judgment more effective by giving credit professionals cleaner, more consistent information to interpret.
This becomes increasingly important as lending volume grows. Maintaining strong credit quality across more files, analysts, and borrower relationships requires data quality that can remain consistent at scale.
Creating a Stronger Data Foundation With FlashSpread
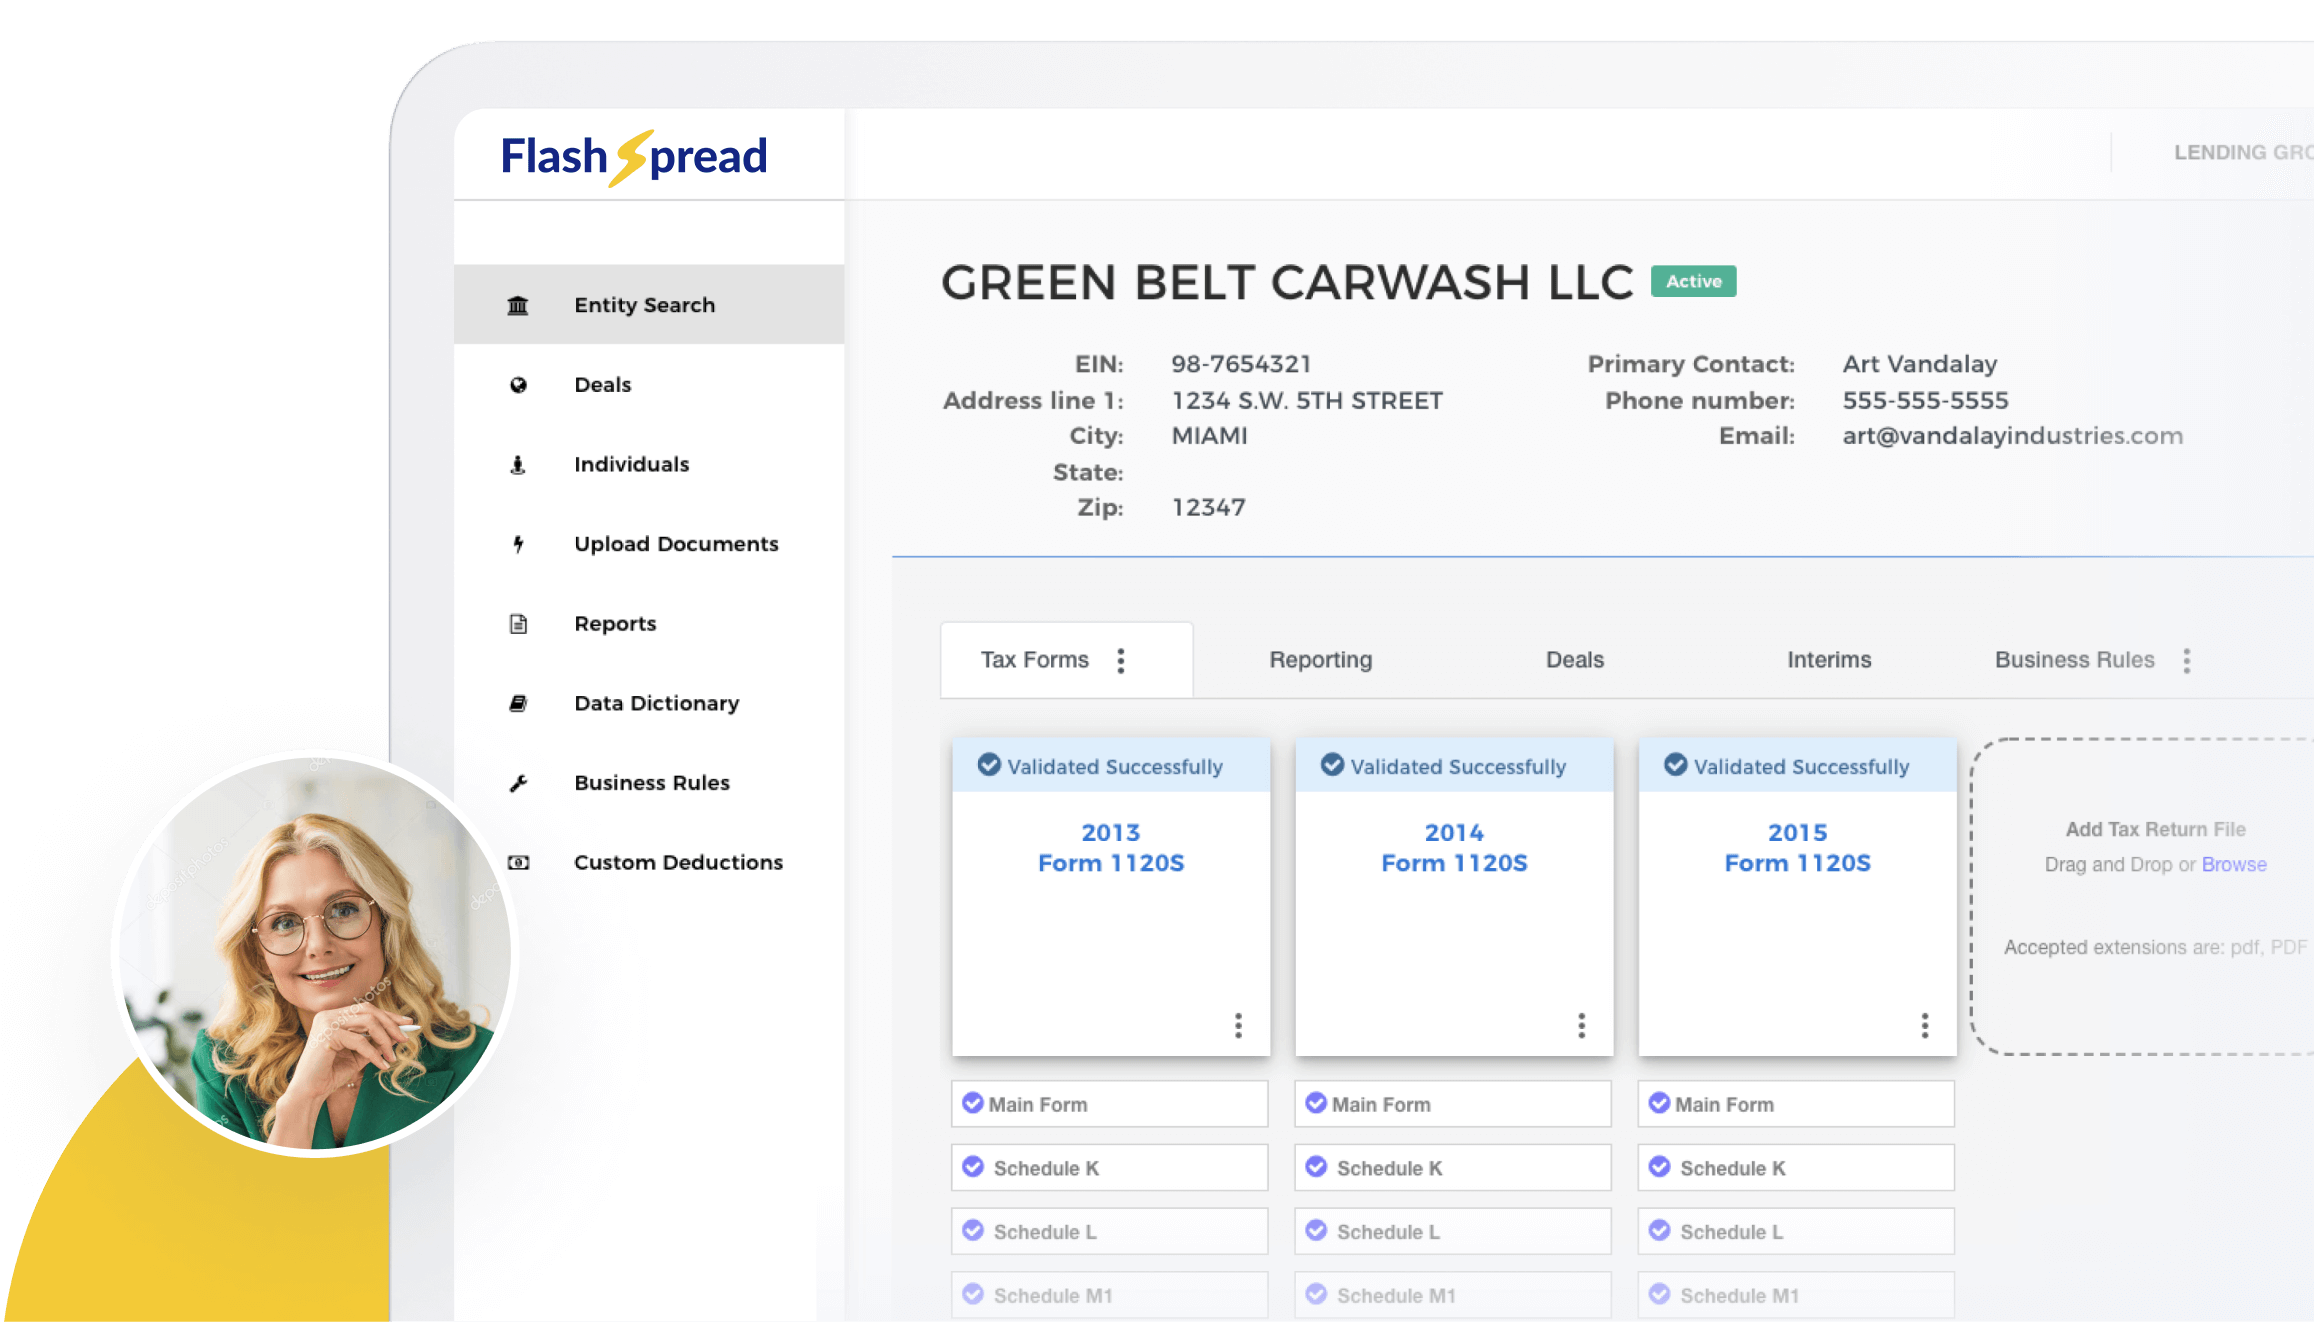
FlashSpread helps commercial lenders turn borrower documents into standardized, decision-ready financial data before credit analysis begins.
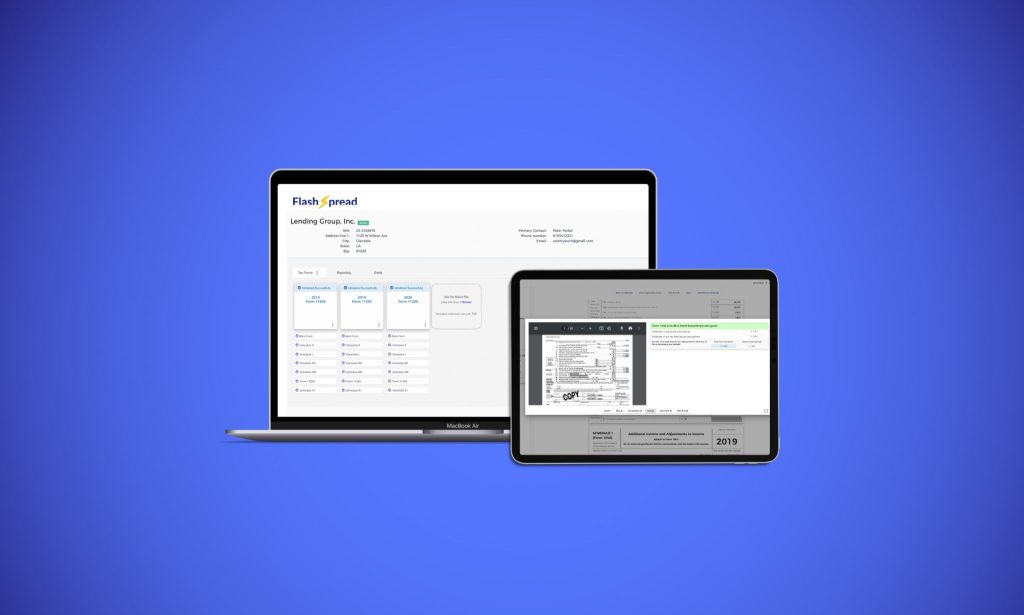
The business outcome is a stronger and more consistent starting point for credit decisions.
By improving financial preparation, institutions can:
- Standardize financial information across borrowers and deals
- Reduce unnecessary variation before analysis begins
- Identify missing or inconsistent information earlier
- Give analysts cleaner financials to verify and evaluate
- Support more consistent analysis, reporting, and portfolio monitoring
The goal is not to replace analyst judgment. It is to improve the financial foundation on which that judgment is applied.
When credit professionals begin with cleaner, more consistent data, they can focus their attention on understanding borrower performance, investigating meaningful exceptions, evaluating risk, and making informed lending recommendations.
Conclusion
The quality of credit analysis depends in part on the quality of the financial data behind it.
Inconsistent categorization, calculations, reporting periods, or financial preparation can change the picture analysts use to evaluate a borrower. More checking may catch individual problems, but stronger credit quality begins with improving the consistency of the inputs themselves.
Standardized financial spreading gives analysts a more reliable foundation for borrower comparisons, trend analysis, and risk evaluation. It helps credit teams distinguish meaningful changes in borrower performance from variation introduced during preparation.
FlashSpread helps commercial lenders prepare standardized, decision-ready financial data faster, giving analysts a stronger foundation for the judgment and analysis that follow.
How strong is the data foundation behind your credit decisions? See how FlashSpread helps lenders move from borrower documents to cleaner, more consistent financial data for analysis.